Jim’s 18 Commandments of Investing

Screenshot 2023-09-06 110140

Why do you invest … hopefully to make money.

Why money … well it can help you achieve goals in life and provide you with a sense of security and freedom.

What makes some investors better than others? Sometimes it just to have a better plan.

Over the course of my career—building businesses as a tech CEO, mentoring entrepreneurs on the board of SCORE, leading a local community investment club for over 10 years, and spending tax seasons as an advanced IRS-certified volunteer tax preparer—I have seen the good, the bad, and the downright ugly sides of personal finance…

Continue reading →

Build Your Own Annuity

Screenshot 2022-04-08 124656

Summary

  • An annuity can provide a steady stream of reliable income during retirement
  • You can build your own annuity with benefits not available elsewhere
  • Dividends completely cover my Required Minimum Distributions and the principle continues to grow
  • Commercial annuities invest if the same types stocks and bonds you can purchase
  • Commercial annuities have substantial fees, end of life limitations and no return of capital
  • My investments include a taxable account, ROTH IRA and a IRA. This article covers my IRA “annuity”
Continue reading →

BEWARE – Large Mutual Fund Taxes This Year!

Taxes

Do You Own Mutual Funds – Just Beware

This is only for people who own mutual funds in a taxable account. This year some people will get clobbered with a huge tax bill and our mutual fund is losing money. They call it adding insult to injury. If you own ETF’s instead, you don’t have this problem.

So how does this happen? It’s almost a perfect story, one you won’t like. Many mutual funds had substantial gains earlier this year, then the market started to turn south and a massive number of people sold. How do we know this, well if the mutual fund price drops 25-30% like the rest of the market, then a massive number of people sold!

Continue reading →

Understanding a Real Oil/Gas Problem – Look at Refinery Closings

download

Summary:

  • Large numbers of refineries have closed
  • Policy-driven Global Warming have forced refineries out of business
  • No one is going to build a new refinery
  • We need a better policy-plan for the future
  • The US should be the world leader in energy of all types, including fossil fuels

Let’s look at a critical component of the overall US Oil/Gas infrastructure – refineries.

Most of you know, the price of oil, natural gas, gasoline and diesel is set by the global futures market …. NOT BY OIL COMPANIES

Continue reading →

The Real Inflation Story – Part 1

mail

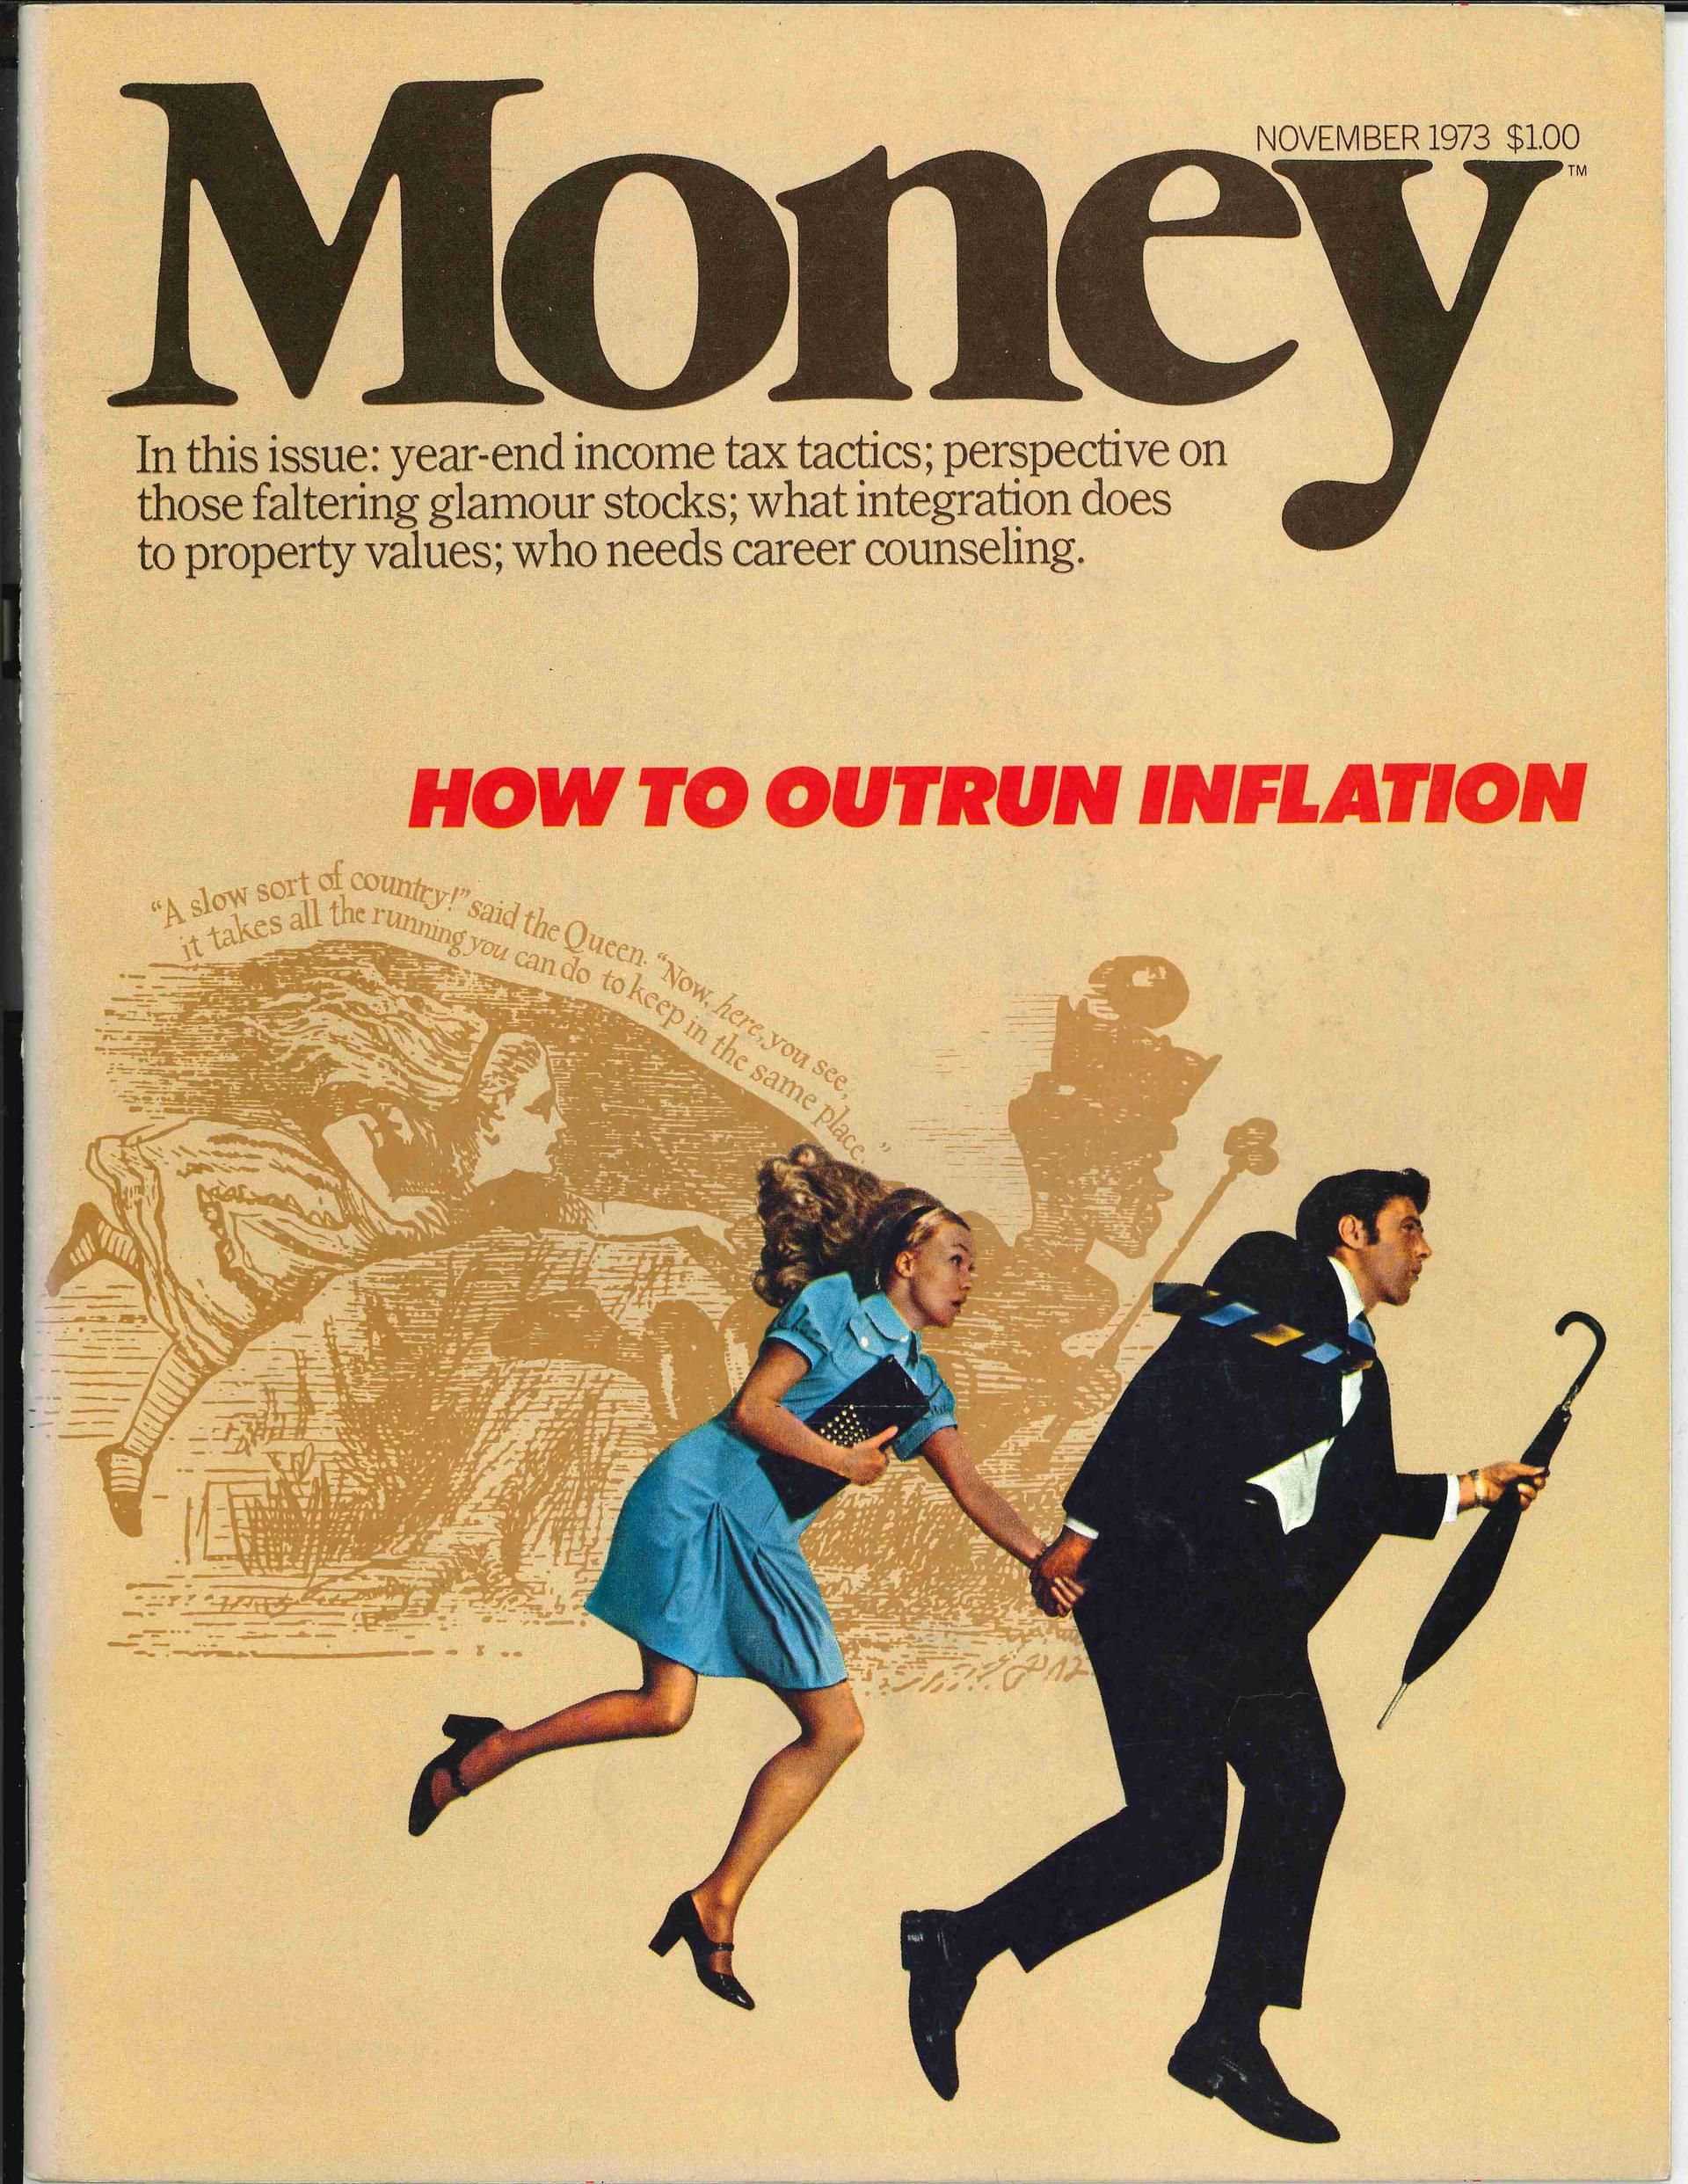
Yes, this is the cover a 1973 Money Magazine about a year after it started publishing. Easy money policies of the Fed are designed signed to generate full employment. However by the early 1970s inflation forced the Fed to raise interest rates to almost 20%! This inflation spiral lasted almost 10 years as we went into a bad recession.

Since we are a consumer driven economy, high inflation crushes our spending power, it tends to be a spiraling process. What has traditionally stopped inflation …. a RECESSION.

Here is what you should know about our current situation.

Continue reading →

Guess Who Isn’t Getting a $1,200 Check – Your College Students and Others!

students.JPG

We all know that the Economic Impact Payments will be giving us $1,200 per adult and parents get $500 for each dependent under age 17. (subject to income limits)
That leaves out anyone 18 and older, who can still be claimed as dependents on another person’s tax return.

A taxpayer is allowed to claim a full-time student between the ages of 19 and 24 as a dependent, so the parent will not get $500 for a college student, nor can the college student generally claim $1,200. Also anyone supporting adults with disabilities and elderly dependents also will not qualify for the additional $500 check!

Furthermore, the you have to have filed a tax return to get your $1,200. Many low income and senior citizens currently don’t file, they are not required to do so. The IRS is saying that they now have to file basic information to get their checks.

While on the topic of college students, I hope parents know how to get the maximum American Opportunity Credit by claiming the right “Qualified Educational Expenses” on their returns and letting the student show the most “scholarship income” on their returns

Did you change bank accounts since your last tax filing? If so the Treasury will build a web site to allow you to make this adjustment.

The IRS has a new web site dedicated to the details of the Coronavirus Tax Relief, https://www.irs.gov/coronavirus


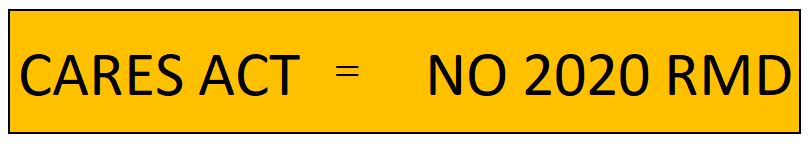
NO RMD in 2020 – Little Known Benefit

NO RMD.JPG

Among the good and bad provisions of the massive Coronavirus Aid, Relief, and Economic Security Act or CARES Act, are waivers for your 2020 required minimum distributions (RMD). Many people don’t need this money for day to day expenses, but they have to take it anyhow. 

Who Does This Apply To?

If you have to take a RMD in 2020 from any plan. for example a 401(k) or your IRA the new law says you no longer have to take it in 2020. Also included are beneficiaries, and including those who turned age 70 1/2 in 2019 and had to take their first RMD by April 1, 2020.

Benefits and An Interesting Strategy:

  1. As we all know our 2020 RMDs were sky high. Our 2020 RMDs were based on our retirement account values on December 31, 2019, when the Dow was over 28,000, now it is around 22,000. 
  2. When you take your RMD you pay income tax on it at the ordinary income rate and it increases the amount of your Social Security that is taxable and it can roll you into a higher tax bracket for dividends and capital gains. You get NO special tax treatment for RMD.
  3. STRATEGY – since you don’t have to take an RMD, you could decide to take advantage of this situation to do a ROTH conversion. First of all, any amount converted removes those funds from your IRA, lowering the balance that will be subject to your future RMD, therefore lowers your income and tax bill for future years. Secondly, once the funds are in your Roth IRA, they will become lifetime tax free. Your Roth will also pass income tax-free to your beneficiaries. Most importantly, converting now when market values have dropped will mean that any future rebound will now accumulate tax free to you in your Roth IRA. Which is better, price appreciation of a stock in an IRA or a ROTH? ROTH!!!!!!
  4. Yes, a ROTH conversion is taxable as ordinary income, just like a RMD! However, today we may be paying mush lower taxes that we will be in future years as we pay for all of this new government spending.

download.jpg


Refinance Everything Immediately & a Fix for the China Problem

Refinance-1

Summary
Interest rates are so low that now is the time to refinance everything and deal with China! If you have any debt whatsoever refinance it now. This might be a once-in-a-lifetime opportunity.

–          Your home mortgage and all credit card debt

–          New methods for a mortgage/refinance – completely on-line

–          REFINANCE THE NATIONAL DEBT

–          Easy way to deal with China

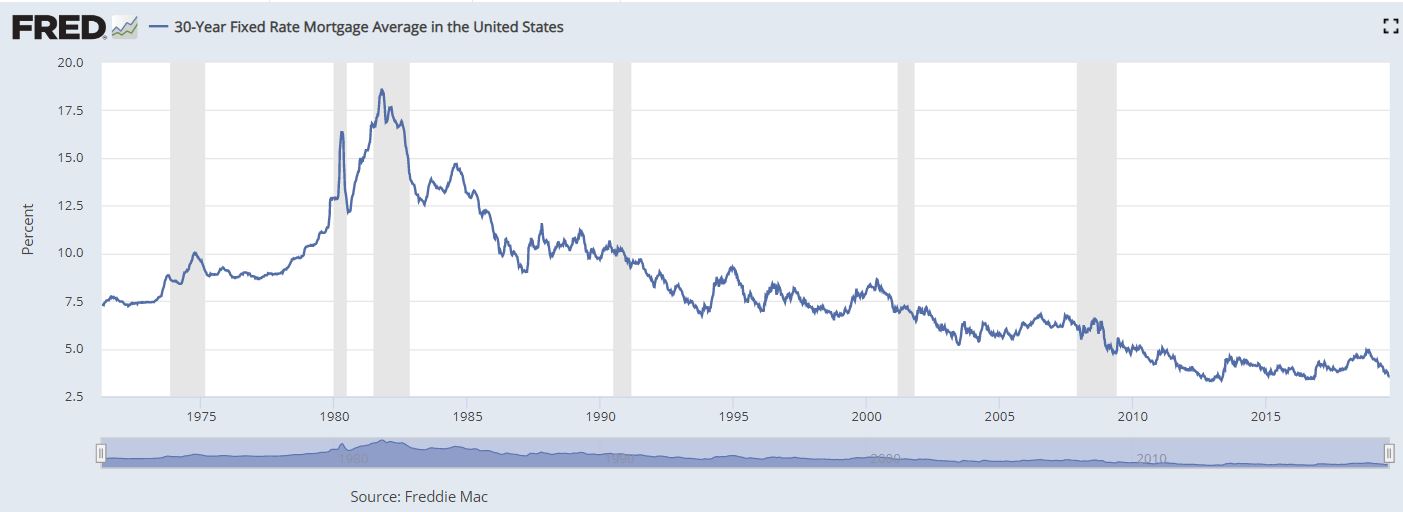
Home mortgages with interest rates 4.5% or higher should be refinanced. The outright savings can be a few hundred dollars a month. Today in Florida you can get a 3.5% refinance rate.

Take a look at the following chart:
Rates Chart.JPG

This is why I say it is a life-time opportunity. I’m 71 years old and bought my 1st house in 1972 at the age of 24, I’ve never seen a 3.5% or lower interest rate. This is historic and won’t last forever.

Now, regarding credit cards and any type of loan, including student loan balances, pay them off.  These rates, in general, do not change. If you have equity built up in your home, refinance it and take out cash to pay off all higher interest rate loans/credit cards. Make sure you keep from ever running up expensive debt. Do not use the extra cash for vacations or just buying stuff. By doing this you will make a meaningful improvement to your cash flow and financial well-being.

New Mortgage Options. There are new companies that offer complete on-line low fee refinancing, the best known is Better.com. There are no commissions and have a very efficient process. When you apply online for the 3-minute basic pre-approval, they will ask for your social security number and do a secure “soft” credit check. This doesn’t affect your credit score in any way. They use your FICO Classic 04 credit score from Transunion. Knowing your credit score helps them make more accurate calculations about how much you can afford. If you have good credit and complete all of the requirements you can lock in your mortgage rate on the SAME DAY. It pays to check their site every day, the rates can change daily. Furthermore, with this new service you can close on a refinance easily within 30 days. They actually have a notary/real estate agent come to your house to sign all of the documents. No more meeting at some title company.

The Government should REFINANCE THE NATIONAL DEBT. The US currently has about $17 trillion in public debt. Doing this could save BILLIONS A MONTH. By “taking out new low interest loans” we can pay off our current liabilities. Right now the short-term bonds/notes are roughly the same as longer-term ones.

Here is the history of 10 year Treasury Notes:10 Year Yeild Chart.JPG
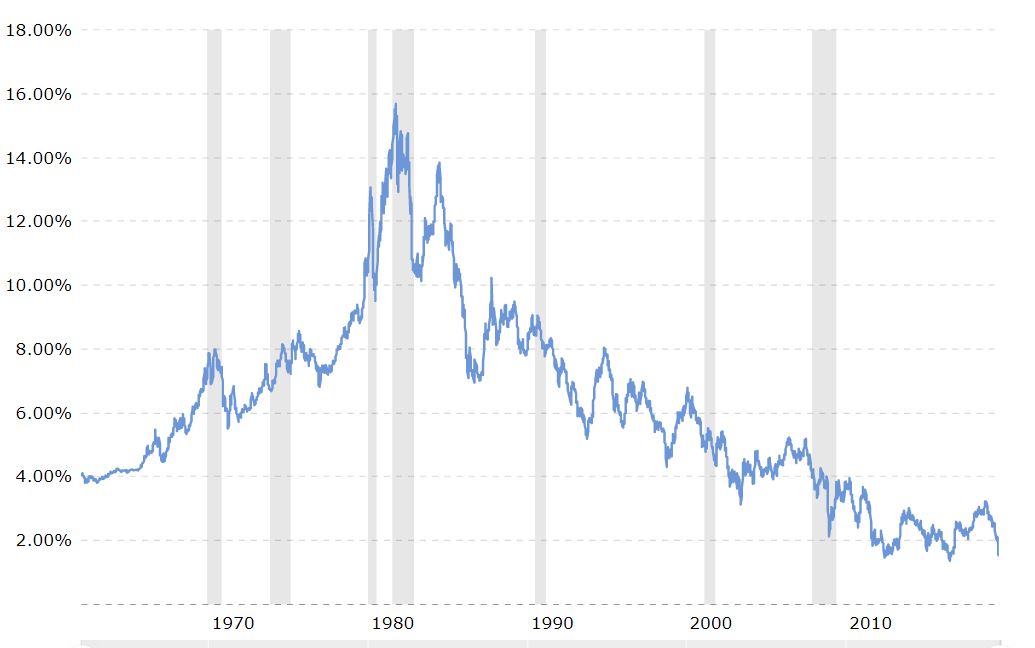
The US can issue very long dated bonds, like 50 or even 100 year bonds at low, locked in rates. Obviously, over the next 50+ years interest rates will rise again. The CBO estimates that for every percentage point reduction in interest rates the US would save about $1.7 trillion over a decade! This would be a huge debt reduction and pretty much painless to the economy.

Easy way to deal with China. There is a really easy way to deal with China, who holds the 2nd most US debt, just behind Japan. Many people are concerned because China owns over $1.11 trillion of US debt, 27% of the $4.1 trillion in Treasury bills, notes, and bonds held by foreign countries. I’m not worried at all. First of all, China cannot just demand payment, these notes/bonds have redemption terms, if it’s a 10 year note, you can have your money back in 10 years. Secondly, China can try and sell these notes/bonds on the open market, but they aren’t exactly fools. These older notes/bonds carry much higher interest rates vs today’s negative rates in most other parts of the world. Besides, China needs lots of US dollars in their foreign reserve account.
download.jpg

HERE IS A SUGGESTION TO CHINA: Hi China, we’ll be calling all of our US debt that you hold, ever bit of it. No more 2 –  5% interest payments on that $1.1 trillion dollars. In addition, since you have been such a good trading partner with the US all of these years we’ll have our Treasury Dept print up a whole new batch of bills, just for you. We will save billions in interest payments, and it won’t cost us a single penny! You can take this $1.1 trillion and go buy negative yielding German Bunds!
 

To Stretch or Not To Stretch – A Real Problem

money flying out of man's wallet

Maybe you have worked all of your life to build a nice IRA to help fund your retirement. In addition, you have set-up an estate plan and trust to make sure your non-spouse loved ones are not just well taken care of, but enjoy the most tax-efficient flexibility possible.

Watch out, congress is trying to tax your IRA sooner vs. later. They are trying to change the rules for “stretch IRA’s”. On May 23, 2019, the US House passed legislation called Setting Every Community Up for Retirement Enhancement Act of 2019, or the SECURE Act.

Example of a Stretch IRA – Current Policy
A person is 70 years old, have a Traditional IRA valued at say $700,000, currently take a RMD (Required Minimum Distribution) and name a 30 year old relative as the beneficiary on their IRA. The RMD and subsequent income for tax purposes is based on their expected remaining life.

Under current tax provisions, if the person passed away today, the 30 year old relative would set-up a new “Inherited IRA” and begin taking RMD based on a life expectancy of 53.3 years (IRS tables). The 1st years distribution will be $13,133 ($700,000/53.3), the relative only pays income on the $13,133!! The Inherited IRA benefits from investments being tax deferred for 53 years, or the RMD is “stretched” over a much longer life span while taking out a much smaller RMD.

Proposed SECURE Act – Changing the RMD to 10 Years
Under the SECURE act Uncle Sam wants to collect their taxes sooner vs later and therefore will require the Inherited IRA to be liquidated in 10 years. Therefore, the annual RMD payment would be $70,000. Now, the relative may like the idea of receiving $70,000 a year, but this will probably toss them into a much higher tax bracket and could cause other unanticipated consequences. The elimination of a “stretch” is a huge disadvantage. Keep in mind that the deceased person probably has an entire estate of other assets that will get transferred to the relative beyond just an IRA. Could your 30-something relative hand this money? 

Eliminating the stretch IRA provisions will have a significant impact on many existing trusts that have been set-up to accommodate IRA retirement plans. Many such trusts allow the trustee to control distributions to the beneficiary based on the timing of RMDs, typically for the life expectancy of the beneficiary. If the SECURE Act is passed, the trustee could be required to distribute the account during the 10-years following the IRA owner’s death, or 10 years following a minor child beneficiary reaching the age of majority, losing the benefit of holding the funds in trust.

Don’t Worry About Your Spouse
The SECURE Act really doesn’t affect your spouse provided your spouse does some pretty simple things. For spouses, not only can they receive distributions based on their life expectancy, they may also “rollover” the inherited IRA into their own IRA, possibly delaying RMDs until the spouse reaches age 70½.

Let’s make sure our law makers don’t get greedy and try to raise our taxes by removing the “stretch IRA” provision!

Caveat: I am not a financial planner and there are many other details to consider in all of these decisions. Please seek help for a tax expert, attorney or certified tax planner before making decisions.